What You Need to Know About Car Rental and Insurance Coverage
When renting a car, another issue that is just as important as the price is the “insurance coverage.” In situations such as scratches, parking damage, broken windows, or traffic accidents that may occur with a rental vehicle, who is responsible for which costs is determined by the insurance/collision damage waiver package you choose and the terms of the rental agreement. For this reason, understanding the insurance coverage correctly before starting the car rental process helps prevent unexpected expenses and ensures a safer rental experience.
What Is Car Rental Insurance Coverage?
Car rental is a practical solution that meets short- or long-term transportation needs without the burden of purchasing a vehicle. However, renting a car is not just about “picking up the vehicle and using it.” Together with the rental agreement, the renter agrees to use the vehicle under certain conditions and, in some cases, assume specific responsibilities. This is where insurance coverage comes into play.
Insurance (often referred to as comprehensive coverage or collision damage waiver) is a type of protection that covers financial losses resulting from risks such as collision, rollover, fire, or theft. For rental vehicles, insurance is usually offered as a “package,” and its scope may vary from company to company. In car rental, insurance coverage generally includes the following:
- Damage to the rental vehicle: Body damage may be covered under specific conditions.
- Deductible/excess: Even with insurance, the renter may be required to pay a certain amount.
- Additional coverages: Extra packages may be available for glass, tires, headlights, or mirrors.
- Procedural requirements: Reports and timely notifications may be mandatory in case of damage.
In short, insurance coverage defines how potential risks and expenses will be handled if something happens to the rental vehicle. Therefore, when renting a car, not only the daily rate but also the insurance details should be carefully evaluated.
What Does Rental Car Insurance Cover and Not Cover?
Rental car insurance typically covers a significant portion of material damage to the vehicle under certain conditions. However, having “insurance included” does not mean that you will never have to pay anything. The coverage, deductible, and contract terms are decisive factors.
Insurance generally covers:
- Collision/impact: Body damage resulting from a traffic accident (subject to terms).
- Parking damage: Damage occurring while the vehicle is parked (in some packages).
- Fire: Fire-related damages (depending on policy scope).
- Theft: Theft of the vehicle or damage resulting from attempted theft (subject to conditions).
- Natural disasters: Flood, hail, storm, etc. (if included in the coverage).
Insurance often does not cover or limits coverage in cases such as:
- Contract violations due to driver fault: Driving under the influence, unlicensed driving, racing, reckless use.
- Late reporting: Failure to report damage/accidents on time or incomplete documentation.
- Unauthorized driver: Use of the vehicle by someone not listed in the contract.
- Intentional damage: Deliberate harm to the vehicle.
- Off-road or improper use: Using the vehicle in ways that violate the rental agreement.
The key point is that although insurance coverage may seem similar in general terms, each rental company has different package structures and contractual conditions. Therefore, you should clearly understand not only what is included, but also what is excluded.
What Is a Deductible and How Does It Affect Rental Costs?
The deductible (also called excess or liability amount) means that even if insurance applies, the renter is responsible for paying a certain amount in case of damage. For example, if the total damage is $3,000 and the deductible is $500, the renter may be required to pay $500 while the remaining amount is covered by insurance (subject to terms).
The deductible affects rental costs in two main ways:
- Daily rate: Packages with higher deductibles usually have lower daily rental prices.
- Risk exposure: As the deductible decreases (or is reduced to zero), the daily rate increases, but your potential out-of-pocket cost in case of damage decreases.
Practical tips for choosing the right deductible:
- If usage intensity is high (long-distance trips, frequent city parking), a lower deductible may be safer.
- If multiple drivers will use the vehicle (such as a company car), risk increases and coverage choice becomes more important.
- In busy seasons and heavy traffic (large city centers), the likelihood of minor damage may be higher.
In short, the deductible answers the question: “How much responsibility do you still have even if insurance is included?” Choosing a package without understanding the deductible is one of the most common causes of dissatisfaction.
Types of Insurance in Car Rental: Mandatory Liability and Additional Coverages
In rental agreements, two main insurance areas are usually discussed: mandatory liability insurance and comprehensive coverage/additional protections. These are often confused but have different scopes.
Mandatory liability insurance:
- Covers damage caused to third parties.
- Protects against damage to the other vehicle or injuries to third parties within policy limits.
- Does not directly cover damage to the rental vehicle itself.
Comprehensive coverage (collision damage waiver):
- Covers damage to the rental vehicle itself under certain conditions.
- Focuses on risks such as collision, fire, and theft.
- Includes deductibles, procedures, and exclusions.
Additional coverages (depending on the package):
- Minor damage protection: Covers small scratches and dents more easily.
- Glass-headlight-mirror coverage: These parts may require separate coverage.
- Tire and rim protection: Covers issues like pothole or curb damage.
- Personal accident insurance: Additional protection for driver and passengers.
- Extended liability: Increases coverage limits for third-party damages.
When renting a car, it is important to clarify what “insurance included” actually means: liability insurance, comprehensive coverage, or additional protections? If this distinction is unclear, misunderstandings may arise.
What to Consider When Choosing an Insurance Package
Choosing the right insurance package directly affects your rental experience. The right package helps control daily costs while ensuring that you are not burdened with high expenses in case of damage. The best decision is made based on your intended usage scenario.
Checklist when selecting a package:
- What is the deductible amount? Is your maximum liability clearly defined?
- Is minor damage covered? How are scratches and bumper scuffs handled?
- Are glass, headlights, and mirrors included?
- Is theft and natural disaster coverage included?
- Authorized driver requirement: Is an additional driver properly registered?
- Procedural obligations: Are reporting deadlines and documentation requirements clearly stated?
Quick suggestions based on usage:
- Heavy city traffic: Minor damage protection and low deductible may be beneficial.
- Long-distance travel: Accident procedures, roadside assistance, and replacement vehicle terms are important.
- Busy parking areas: Coverage for parking damage and minor scratches is valuable.
Does Insurance Cover Minor Scratches and Parking Damage?
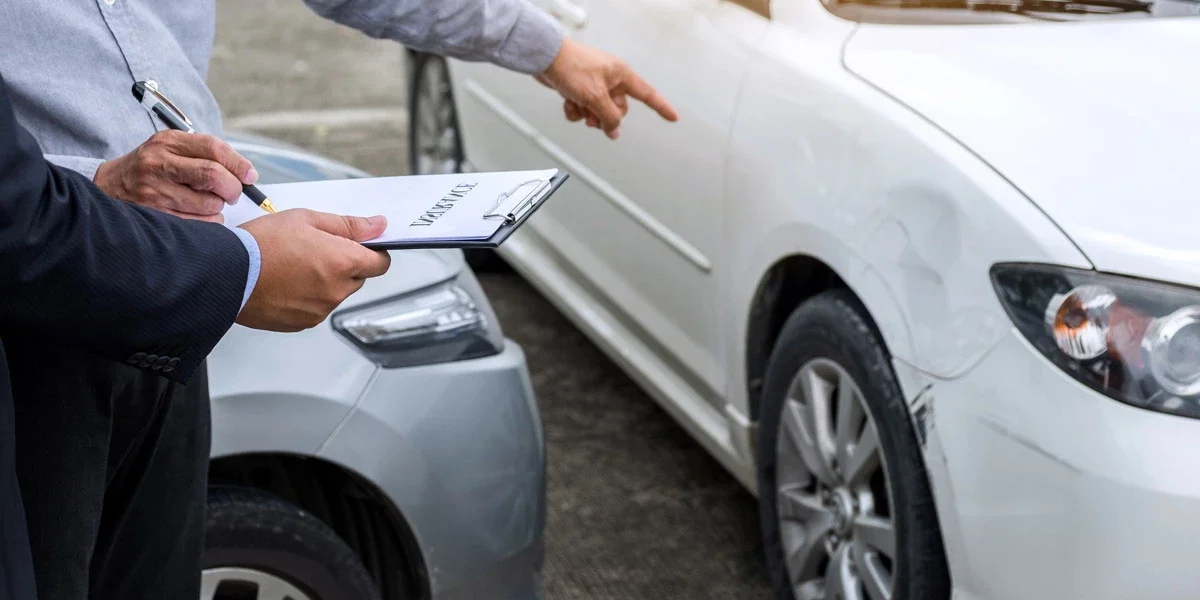
Minor damage is one of the most frequently asked topics in car rentals. Small bumper scuffs, door scratches, dents, and rim scratches are common in city use. Whether these are covered depends on the selected package and contract terms.
Factors affecting minor damage coverage:
- Package content: Some packages include minor damage protection; others do not.
- Extent of damage: There may be size or quantity limits.
- Part type: Bumpers and body panels may be treated differently from glass or headlights.
- Documentation: How damage is reported and recorded at pickup and return matters.
Practical tips:
- Take photos when picking up the vehicle (especially bumpers, rims, and doors).
- Ensure existing scratches are noted in the delivery form.
- Avoid tight parking spaces whenever possible.
Are Theft, Broken Glass, and Natural Disasters Covered?
Theft, broken glass, and natural disasters are not always included in the same way in standard insurance packages. In some policies, they are included; in others, they are optional add-ons. Although these risks may seem unlikely, they can result in significant costs.
Theft coverage typically includes:
- Theft of the vehicle
- Damage resulting from attempted theft
However, negligence such as leaving the key inside the vehicle or failing to lock doors may void coverage.
Glass damage may include:
- Windshield cracks from stones
- Side window breakage
- Rear window damage
In many cases, additional coverage is required.
Natural disasters (depending on policy):
- Flood and water damage
- Hail and storms
- Earthquake
What to Do in Case of an Accident
Taking the correct steps during an accident is critical for insurance coverage to apply smoothly. Rental insurance is usually procedure-based, meaning proper documentation and timely notification are required.
- Ensure safety: Turn on hazard lights and move to a safe area if possible.
- Call emergency services if there are injuries.
- Contact the police if required.
- Complete an accident report.
- Take photos/videos: Capture vehicle positions and damage details.
- Inform the rental company immediately.
- Follow authorized service/towing instructions.
Common Mistakes Regarding Rental Insurance
- Assuming “I’m fully covered no matter what.”
- Not reading the contract carefully.
- Failing to take photos at pickup.
- Allowing unauthorized drivers to use the car.
- Late reporting of accidents.
- Improper use of the vehicle.
Frequently Asked Questions About Rental Insurance
- Is insurance mandatory when renting a car?
Most rentals include a basic insurance structure, though requirements may vary. - Will I pay anything if there is insurance?
If there is a deductible, you may be responsible for a certain amount. - Are small scratches covered?
They are better covered under minor damage protection packages. - Is broken glass included?
Sometimes included, sometimes offered as an add-on. - What should I do first after an accident?
Ensure safety, document the incident, and inform the rental company promptly. - Is coverage valid if someone else drives the car?
Usually only authorized drivers listed in the contract are covered.
Understanding rental insurance coverage correctly protects both your budget and your peace of mind. Especially if you will be driving in heavy traffic, on long trips, or in crowded parking areas, clarifying deductible amounts, minor damage coverage, glass and headlight protection, and accident procedures before renting is the safest approach. This way, you can travel with confidence and avoid unexpected expenses.